“AI will be a major component in our industry,” says Annie Ives, CEO of Vesta Plus, reflecting on the future of Multiple Listing Services (MLS) and property data management. “I don’t think AI will replace the agent. AI will become your assistant, but on a high level, not on a smaller, lower level.”
With nearly three decades at the helm of what began as a struggling MLS with just 1,700 agents and has evolved into a technology powerhouse, Ives has a unique perspective on the evolution of property data management in real estate. Her journey from accountant to tech CEO illustrates how vision and persistence can reshape an industry from the inside out.
An Unlikely Tech Pioneer
Ives’ path to becoming a real estate technology leader was anything but conventional. “My background is more Finance, Accounting. That’s how I started in business,” she explains. In 1993, she joined an MLS company as an accountant, drawn partly by the convenience of its location near her home and her children’s school.
When competition threatened to put the company out of business, Ives was called back to help revive it. “From one state to another, our competition went out of business, and we prevailed,” she recalls.
What makes her story particularly remarkable is that she had no technology background when she made a pivotal decision that would shape the company’s future: “I decided that I wanted to write my own software.”
This was a bold move in an industry where most MLSs relied on third-party vendors. Starting with just two programmers who had previously worked on the help desk, Ives began developing proprietary software while still using a third-party vendor solution.
The transition wasn’t smooth. When their contract with the vendor was about to expire, one of her programmers warned they weren’t ready to cut over to their own system. Ives stood firm: “No, we’re not going to renew. We’re going to cut over.” She admits, “It was a little bit of a disaster. But, you know what? I don’t know how we survived it all.”
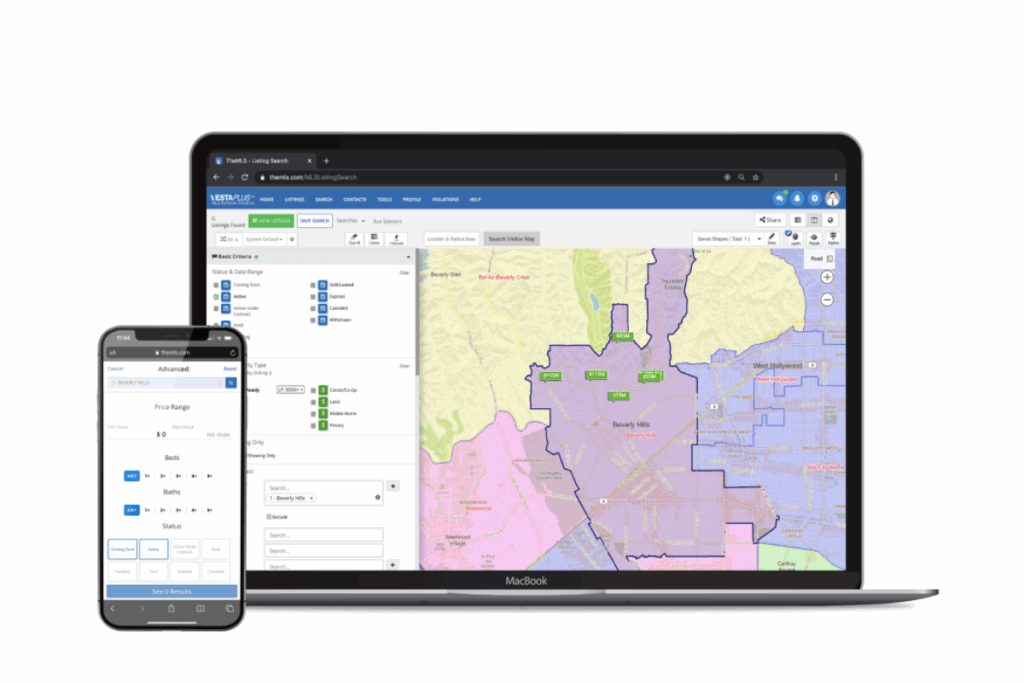
That early software, called MLS Pro, eventually evolved into Vesta Plus. Today, Ives leads a robust technical team with programmers, QA specialists, and database experts, supplemented by outsourced talent in India and Argentina.
Building a Technology Ecosystem
What began as a single MLS system has expanded into a comprehensive suite of real estate technology solutions. “We have many products, besides our main core MLS system,” Ives explains. “We have an app, a compliance software, a showing software. We have a statistics software.”
This diversification strategy has paid dividends, particularly with their compliance software, CheckMate. Rather than marketing their entire platform as a single solution, Ives decided to promote each component individually. “I don’t know why, I got up in the morning and I said, why don’t we start with CheckMate?” The decision proved successful, with the software now used by numerous MLSs across the country, including “beaches in Florida, San Diego” and many others.
Ives credits much of the technical success to her CTO, Santanu Barua, who has been with her for 20 years. “He is very smart. There’s nothing he cannot resolve,” she says.
Beyond technology, Vesta Plus also ventured into publishing. At the request of broker Jeff Hyland (of Hilton & Hyland), Ives launched a real estate magazine that has become a significant revenue generator for the company. “During COVID, we thought that the magazine was going to suffer because everything is digital. But I just want to say that we still generate substantial revenue from the magazine.”
The Value of Clean Data
When asked why she continues to invest in MLS technology, often considered a thankless job, Ives’ enthusiasm is evident: “I find it very exciting. You know, I come in the morning and I just have all kinds of ideas.”
At the core of her passion is a commitment to data quality. “If you feel the core business of an MLS is data, and it’s accuracy of the data… our asset, the asset of the MLS, is data accuracy, accurate data. That’s the base of an MLS.”
This focus on data integrity explains why platforms like Zillow prefer to get their listings from MLSs rather than individual brokers. “Why does Zillow would rather get the feed from us and not go to multiple brokers to get a feed? Because it will be very difficult, and the data will not be as accurate as we give them.”
Maintaining this data quality is a constant challenge when thousands of agents are inputting information. Vesta Plus’ CheckMate compliance software helps address this by identifying listing violations, but Ives emphasizes that the goal isn’t punitive: “Our goal is not to fine the agent. We do not generate a lot of money from violations… My purpose is to have clean data, accurate data.”
The company continually refines its compliance tools to reduce “false positives,” potential violations that turn out not to be actual infractions. “Every day we make changes to CheckMate, to remove those false positive violations, to make it smarter for us.”
Embracing AI for the Future
Ives sees artificial intelligence as transformative for the real estate industry. Vesta Plus is already implementing AI in several ways:
Photo Compliance: Working with New Zealand-based List Assist, they’re using AI to analyze listing photos for compliance issues.
Automated Listing Input: They’re developing technology that can extract property features from photos and automatically populate listing forms. “From a photo, the features will be already entered into the listing input form. So any feature of a kitchen or whatever will be automatically entered.”
Natural Language Search: Ives believes traditional search parameters will eventually be replaced by conversational queries. “I don’t think that’s the future. The future will be for a consumer or an agent to come in and say, ‘give me all the houses that are around this area, around that kind of price.’ I don’t think that they’re going to come and do a search with all the search criteria anymore.”
This vision aligns with her personal experience using AI tools like ChatGPT, which she uses “all the time, to correct my mistakes or to see if there’s a better version of my writing or even sometimes as my therapist.”
For Ives, embracing these technologies isn’t optional: “If we don’t do it, we’ll be out of business.”
The Future of MLS
Despite predictions about the demise of MLSs, Ives remains confident in their continued relevance. “People feel maybe that we are outdated, we will become obsolete. I think that there will be fewer MLSs in the near future, but I still feel that real estate is local… After my time, I think the MLS will continue to exist, maybe in a different way, but it will continue to exist.”
This perspective comes from someone who has witnessed and driven decades of evolution in how property data is managed and distributed. While Ives acknowledges she will eventually retire, her legacy of innovation continues to shape how the real estate industry handles its most valuable asset: accurate, reliable property data.
This article was sourced from a live expert interview.
Every month we conduct hundreds of interviews with active market practitioners - thousands to date.
Plainfield, Illinois, about 40 minutes southwest of Chicago, spent the last two decades building itself into a family-oriented suburb with good schools, highway access, and prices well below neighboring Naperville. That growth phase worked. Families moved in, raised children, and put down roots. Now many of those original homeowners are entering retirement, and their homes ...
In a city with enough inventory to give buyers real leverage, the segment of the Houston housing market that should be busiest, homes priced between $300,000 and $600,000, is among the slowest to move. Properties below $300,000 are attracting first-time and value-oriented buyers, and listings above $500,000 continue to draw move-up purchasers with less rate ...
Most small mountain towns in the American West have a straightforward real estate story: pandemic-era demand inflated prices, and now those prices are correcting. Taos County, New Mexico, is not following that pattern. Per-square-foot prices there are still climbing, according to Karen Todd, a real estate professional with The Dragonfly Group at Berkshire Hathaway HomeServices ...
A declining median price usually signals a cooling market. In Northeast Dallas, the story is more complicated. The number of homes selling in 2026 has actually increased compared to 2024 and 2025, according to Cindy Dunnican of The Dunnican Team at Coldwell Banker Apex, who has worked the Northeast Dallas market since 1998. But the ...
Large builders in Delaware call their homes “affordable” when prices start at $300,000 to $350,000. For workers earning 40 to 80 percent of the area median income, roughly $35,000 to $60,000 a year in Delaware, those numbers don’t work, even with down payment assistance attached. The gap between what programs label affordable and what service-industry ...
Homeowners who bought during the 2022–2023 building boom in parts of southern Dallas-Fort Worth are discovering an uncomfortable reality: the new homes going up next door are priced at or below what they paid. For sellers who need to exit, the math often doesn’t work. Some are coming to the table with cash beyond their ...