Chicago's Condo Market Is Splitting Away From Single-Family Homes


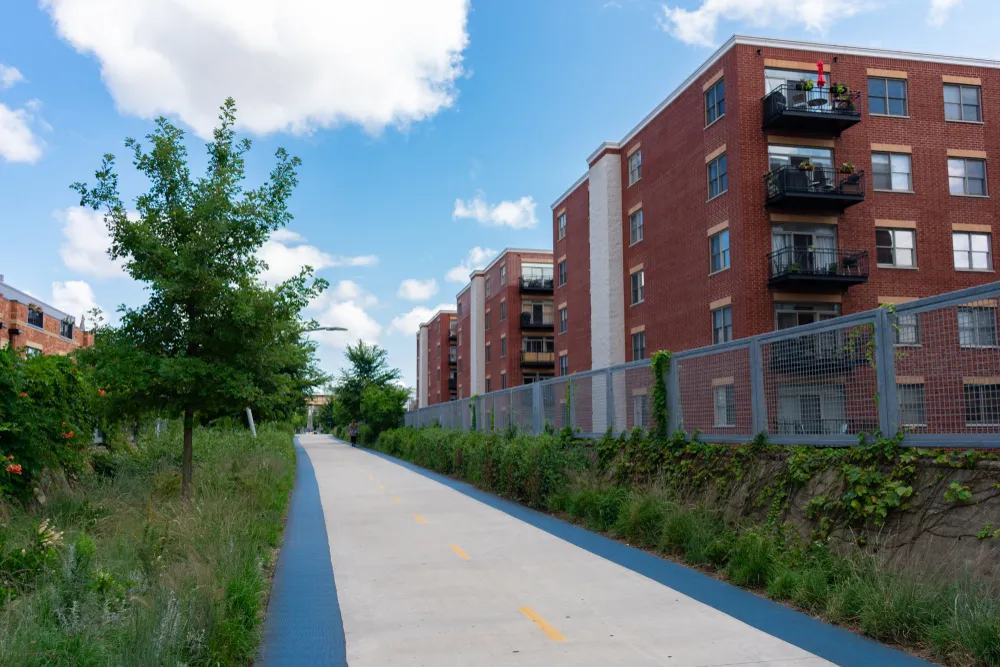
In the Chicago suburbs, single-family homes in desirable locations are drawing multiple offers and selling fast. Condos are moving in the opposite direction: inventory is climbing, financing is getting harder to secure, and sellers are increasingly offering concessions. The gap between the two segments is widening, and the forces driving it apart show no sign of reversing.
Zohaib Khurshid, a listing agent with RE/MAX Premier covering the Chicago metro area, has watched condo inventory grow even as single-family supply stays tight. The result is two distinct markets operating within one metro area as of fall 2026.
Insurance and Assessments Are Changing the Math
The pressure on the condo market is not coming from a lack of buyer interest. It is coming from the costs behind every condo transaction. Zohaib points to insurance premiums and special assessments as the primary drivers. When a condo association faces a large unexpected repair, a roof replacement, structural work, or a building system failure, owners can be hit with assessments running into thousands of dollars with little warning.
Zohaib draws a parallel to Florida, where the condo market has been severely damaged by this pattern. Natural disasters drive up repair costs, owners absorb special assessments they cannot control, and insurance premiums rise in response. “A lot of those natural disasters that kind of hit the coast and then people get hit with the random special assessments,” he says – costs that are “completely beyond their control.”
Chicago does not face the same hurricane exposure, but the underlying dynamic is similar. Aging condo buildings require costly maintenance. When those costs hit owners as lump-sum assessments, they change the financial profile of the unit – and they change how lenders evaluate the risk of writing a mortgage on it.
Lenders Are Pulling Back
That lender caution is where the condo market’s problems become structural. Zohaib says lenders “are becoming a little bit tighter when it comes to offering financing on those condos.” When an association has a history of special assessments, underfunded reserves, or sharply rising insurance premiums, some lenders restrict or deny financing on units in that building entirely.
For buyers, that means fewer loan options and potentially higher costs to close. For sellers, it means a smaller pool of qualified buyers who can actually complete a purchase. Zohaib says financing issues and HOA costs are among the top reasons deals fall apart in the condo space. When a buyer’s lender flags the association’s financial health, the transaction can collapse regardless of how much the buyer wants the unit.
This dynamic helps explain why condo inventory is growing while single-family inventory stays flat. Owners who sense the tightening are trying to sell before conditions worsen. As Zohaib puts it, “a lot of people are looking to get out; they’re looking to upsize.” More condos hit the market, fewer qualified buyers absorb them, and sellers face growing pressure to offer concessions.
What Buyers and Sellers Should Know
Zohaib says concessions in the condo market have become more common over the past couple of months. Sellers who are not receiving the offer volume they expected are increasingly willing to negotiate – a shift that has not reached the single-family market in high-demand suburbs, where multiple offers remain the norm.
For condo buyers in the Chicago metro, the financing question now belongs at the front of the process. Before committing to a unit, Zohaib’s experience suggests buyers should understand the association’s reserve fund status, its recent assessment history, and whether their preferred lender will write a loan on that specific building. A condo that looks affordable on a listing sheet can become significantly more expensive once association fees, insurance costs, and potential assessments are factored in.
For condo sellers, the competitive landscape has changed. Pricing needs to account for a narrower buyer pool and the financing hurdles that thin it further. Zohaib says condo sellers in areas without the strongest school districts or prime locations are the most exposed. Single-family homes in suburbs like Naperville, Hinsdale, and Park Ridge continue to move quickly because they combine strong school districts with limited supply. The condo market across the metro area, by contrast, is absorbing the strain of tighter lending standards and rising ownership costs.
Zohaib adds one seasonal factor worth watching. As the market heads into fall and winter, some sellers may pull listings while frustrated buyers – those who lost out in multiple-offer situations during busier months – may see an opening. “They feel like there’s a little bit of hope for them to be able to find a product that matches their needs,” Zohaib says, “simply because most people just don’t want to move during winter.” For condo buyers willing to search in the off-season, reduced competition from other buyers could offset some of the financing challenges that have made the segment harder to enter.
About the Expert: Zohaib Khurshid is a listing agent with RE/MAX Premier in Chicago, Illinois.
This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.
Similar Articles
Explore similar articles from Our Team of Experts.
So you’re moving to a new city, and the research has already begun. You can learn a metro’s prices, tax rates, and school ratings from a thousand miles away. What the research can’t show you is which neighborhood fits the life you’ll actually lead there. Helping you close that gap is now central to a ...
The Department of Veterans Affairs has narrowed the list of property conditions that can hold up a VA-backed purchase. Under an update to the VA’s Lender’s Handbook, appraisals ordered from May 1, 2026, no longer require repairs for peeling paint on homes built in 1978 or later, or for defects in detached sheds and garages. ...
When 60 to 70 percent of buyers in a market are spending accumulated real estate wealth rather than current earnings, the market operates by different rules than national economic indicators suggest. In Santa Barbara, that disconnect between price levels and income-based affordability is not a temporary distortion – it is the market’s defining feature, according ...
In most of Bucks County, Pennsylvania, the housing market runs on familiar suburban logic: limited inventory, competitive bidding, and first-time buyers stretching to qualify. In Pipersville, at the county’s northern edge, the math works differently. Farms outnumber listings, acreage is measured in dozens rather than fractions, and the buyers who show up are coming from ...
Prospective homebuyers waiting for mortgage rates to fall may be waiting for conditions that only a major global crisis would create. Current 30-year fixed mortgage rates of about 7.25% are not an anomaly, according to Jason Huerkamp of Huerkamp Home Group in the Twin Cities. That figure matches the historic 50-year average. The low rates ...